
Posted January 06, 2023

By Matt Insley
Auto Loans: Extremely Sinister & Incredibly Shoddy
Every Wednesday, Paradigm’s team of editors gather on Zoom for an hour-long, freewheeling discussion about current events, mainly related to the wild world of finance.
During this week’s meeting, when Paradigm analyst Dan Amoss mentioned a few “R” words, I snapped to attention.
The words? Recession… Real-estate foreclosures… and Repossessions (of the auto variety).
That last was a topic we last touched on in November when we cited a stat from the Consumer Finance Protection Bureau (CFPB)...
“When looking at delinquency in the first two years after purchase, loans originated in 2021 and 2022 are starting to show higher delinquency rates relative to loans originated in previous years.”
ConsumerAffairs connected the dots: “Now that the stimulus money has been spent and the extra unemployment benefits have expired, some consumers who overspent on a vehicle are struggling to keep up with payments, especially now that inflation makes everything else more expensive.”
And you might find it hard to believe (or not) what everyday Americans are paying for their vehicles these days…
Send your opinions to, feedback@newsyoucanacton.com
Your Rundown for Friday, January 6, 2022...
“Extremely Alarming”
According to KBB.com, the average monthly payment for a new vehicle — purchased in November last year — is now an eye-watering $762.
Not to get too in the weeds here, but the average full-time individual income in the U.S., circa 2022 was $54,132, per the Bureau of Labor Statistics.
Parsed out monthly, that’s $4,511. Meaning, the average monthly car payment now equals 17% of an individual’s monthly take-home pay.
Is it just me… Or is that nuts? Particularly for an asset that depreciates quickly over time — in some instances, by as much as 30% year-over-year.
But there’s a deeper story that the mainstream hasn’t really picked up on…
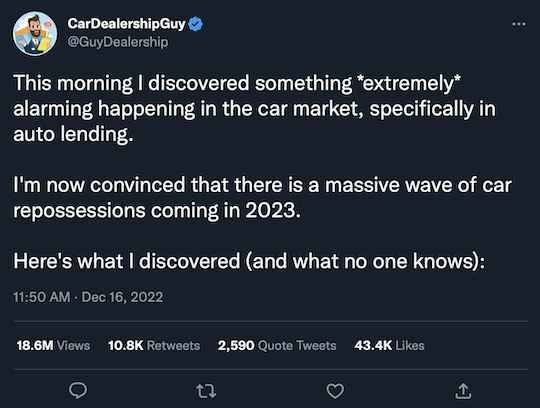
“CarDealershipGuy” on Twitter is an auto-industry insider, and last month, he reported on some truly despicable events taking place in the auto-finance space.
“This morning,” he tweeted, “one of our General Managers… highlighted something very concerning. [Nine] of our lending partners have started WAIVING ‘open auto stipulations’ for consumers.”
He further explained that so many consumers are underwater on their vehicles, but when they try to trade in the vehicle to a dealer, the dealer wants them to cover the difference between the value of the vehicle and the price the dealer can sell it for.
The thing is the consumer doesn’t have thousands of dollars to cover the difference. “Lender knows that most consumers are stuck in this situation, and does the following:
“WAIVES THE OPEN AUTO STIPULATION.
“Meaning, the lender lets the consumer buy the car KNOWING that they already have an open auto loan with another bank!”
Why do this? “Surely the lender knows that consumers that take out a 2nd auto loan are MUCH riskier and have a MUCH high risk of default? Right?
“Yes, but the lender does it because they know that the consumer will default on the other car… Dog eat dog style.
“This is NOT normal,” CarDealershipGuy emphasized. “But it's the only way lenders can finance cars and dealers can put cars on the road.
“And the implications of this will be tons of repossessions,” he says.
In November, we noted how incredibly shoddy auto-loan underwriting was during the early years of the pandemic when 96% of auto-loan consumers didn’t even have their incomes verified, according to Consumer Reports.
Here in 2023, the lenders who signed off on these loans now look less shoddy… and, clearly, more sinister.
Market Rundown for Friday, Jan. 6, 2022
S&P 500 futures are up 1% to 3,845.
Oil is up 1.20% to $74.57 for a barrel of West Texas crude.
Gold is catching a bid this morning, up 1.35% to $1,865.40 per ounce.
And Bitcoin is down 0.40% to $16,700.
Send your comments and questions to, feedback@newsyoucanacton.com

Pink Slip Pete
Posted September 09, 2026
By Emily Clancy

162,000 Jobs, Give or Take
Posted September 07, 2026
By Matt Insley
Buck Sexton: The DSA Has a Pentagon Problem
Posted September 04, 2026
By Matt Insley

When Jim Rickards Spotted a Whale
Posted September 02, 2026
By Matt Insley
The Gates Family Knows How to “Rule”
Posted August 31, 2026
By Matt Insley
