
Posted November 09, 2026

By Emily Clancy
The Risky Business of Life Insurance
“Watch out for that first step. It’s a doozy!”
If you’ve seen the movie Groundhog Day, you probably remember that line from Ned Ryerson, the relentlessly obnoxious insurance salesman who keeps cornering Bill Murray’s character on the streets of Punxsutawney, Pennsylvania.
Groundhog Day happens to be my favorite comedy, and Ned’s attempts to sell Phil Connors a life insurance policy are among my favorite running gags.
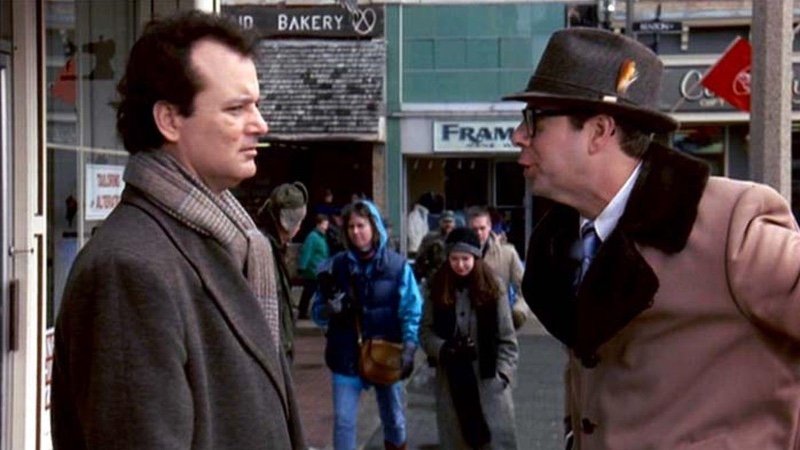
“Needlenose Ned” Ryerson (Stephen Tobolowsky) corners Phil Connors (Bill Murray) with another insurance pitch in the 1993 comedy Groundhog Day. (Image: Columbia Pictures)
No offense to insurance brokers, but I suspect most of us would rather step into that icy puddle than endure an insurance sales pitch.
Still, life insurance is supposed to provide financial security when life takes an unexpected turn.
But what happens when the insurance companies themselves take risks that policyholders know nothing about?
As it turns out, that’s becoming a trillion-dollar question.
Your Rundown for Monday, November 9, 2026...
The Hidden $1.2 Trillion Insurance Exposure
On Thursday, the National Association of Insurance Commissioners (NAIC) released an analysis revealing that U.S. insurers held $1.21 trillion in private-credit investments at the end of 2025.
That represents around 13% of the industry’s cash and invested assets.
Of that amount, regulators identified $544 billion in investments that deserve a closer look because they’re more complicated or involve less familiar types of assets.
So, about private credit…
Essentially, it’s lending that takes place outside traditional banks. Instead of borrowing from a bank, businesses get loans directly from investment firms, often with less public disclosure than traditional corporate bonds.
Insurance companies have become major players because they collect premiums today and invest that money to pay claims and benefits years or decades down the road.
Private credit can offer attractive returns. But many of these investments are difficult to sell quickly, and figuring out what they’re worth isn’t always straightforward.
Most recently, a November 5 analysis from the Center for American Progress warns that the risks of private credit increasingly extend beyond wealthy investors and Wall Street institutions.
Ordinary Americans can be exposed through pension funds, retirement annuities and insurance policies. And the financial ties aren’t always obvious.
Take Athene, one of the country’s largest providers of retirement annuities. These are insurance contracts that people purchase to provide income during retirement.
Athene is part of Apollo Global Management, a Wall Street investment giant that also manages much of Athene’s investment portfolio.
According to the analysis, Apollo originated 73% of Athene’s investments, while private-credit assets accounted for more than 15% of its total investments.
That doesn’t necessarily mean Athene is in financial trouble. But it illustrates how the money backing ordinary Americans’ retirement and insurance contracts can end up invested in private loans arranged by Wall Street firms.
Now consider another unsettling figure. In March, Fitch Ratings reported that defaults among U.S. corporate private-credit borrowers had reached a record 9.2%.
Still, imagine a severe recession in which borrowers stop paying, private-credit investments lose value and insurance companies suddenly need cash.
The concern isn’t necessarily one bad loan. It’s the possibility that financial trouble spreads from one institution to another because they’re holding similar investments.
Here’s what matters if you have a life insurance policy or an annuity:
First, states regulate insurance companies, requiring them to set aside enough money to pay claims and follow rules that protect policyholders.
If an insurer fails, state safety-net programs generally provide at least $300,000 in life insurance death benefits, $100,000 in cash value from life insurance policies and $250,000 in annuity benefits.
Those are minimum protection levels, not necessarily the maximum amount you could recover. But exact limits and eligibility depend on your state.
For now, the sensible approach is to check your insurer’s financial-strength ratings, understand what your policy actually guarantees and find out how much protection your state provides.
And remember that a familiar brand name isn’t necessarily the actual insurance company responsible for paying your benefits.
The NAIC points out that more than half of insurers’ private-credit investments are in familiar assets that regulators have kept an eye on for decades.
So this isn’t an epidemic of failing insurers. But some companies may be taking financial risks that aren’t obvious to the people counting on them.
Which brings me back to Needlenose Ned.
Insurance is supposed to protect us from life’s unfortunate surprises.
The question today is whether the companies providing that protection are prepared for a few surprises of their own.
Market Rundown for Monday, Nov. 9, 2026
S&P 500 futures are up 0.90% to 7,470.
Oil’s down 3.70% to $87.50 for a barrel of WTI.
Gold is up 1.40% to $4,132.80 per ounce.
And Bitcoin’s down 1.25% to $74,780.

Rickards vs. Altucher: The Nashville Showdown
Posted November 06, 2026
By Matt Insley

Kissin’ Cousins, $7 Eggs and Creeps
Posted November 04, 2026
Wall Street’s IPO Darling Needs More Juice
Posted November 02, 2026
By Dan Amoss

America’s Red Reformation
Posted October 30, 2026
By Matt Insley
Jim Rickards, Unscripted
Posted October 28, 2026
By Matt Insley
